
Ammonia: IEA 8 Million Barrel/Day Surplus Forecast for 2027 — Long-Run Nitrogen Production Cost Signal
Introduction
Ammonia sits at the foundation of the global nitrogen fertilizer industry. Every major nitrogen product—urea, ammonium nitrate, UAN, and ammonium sulfate—depends directly or indirectly on ammonia production economics. As a result, any shift in global energy markets eventually influences fertilizer pricing.
One of the most important long-term signals for the ammonia market is the International Energy Agency's (IEA) forecast of an 8 million barrel-per-day global oil supply surplus in 2027, assuming full normalization of traffic through the Strait of Hormuz and continued growth in global energy production.
While ammonia prices remain influenced by near-term supply disruptions, this forecast points toward a potentially lower-cost production environment in 2027.
Why Energy Costs Matter for Ammonia
Ammonia is one of the most energy-intensive chemicals produced at industrial scale.
Production pathway:
Natural Gas → Hydrogen → Ammonia (NH₃)
Cost structure:
In many regions, natural gas accounts for:
60–80% of ammonia production costs
The largest variable cost component
The primary driver of profitability
Because natural gas pricing is often linked directly or indirectly to oil markets, long-term energy trends have a major influence on ammonia economics.
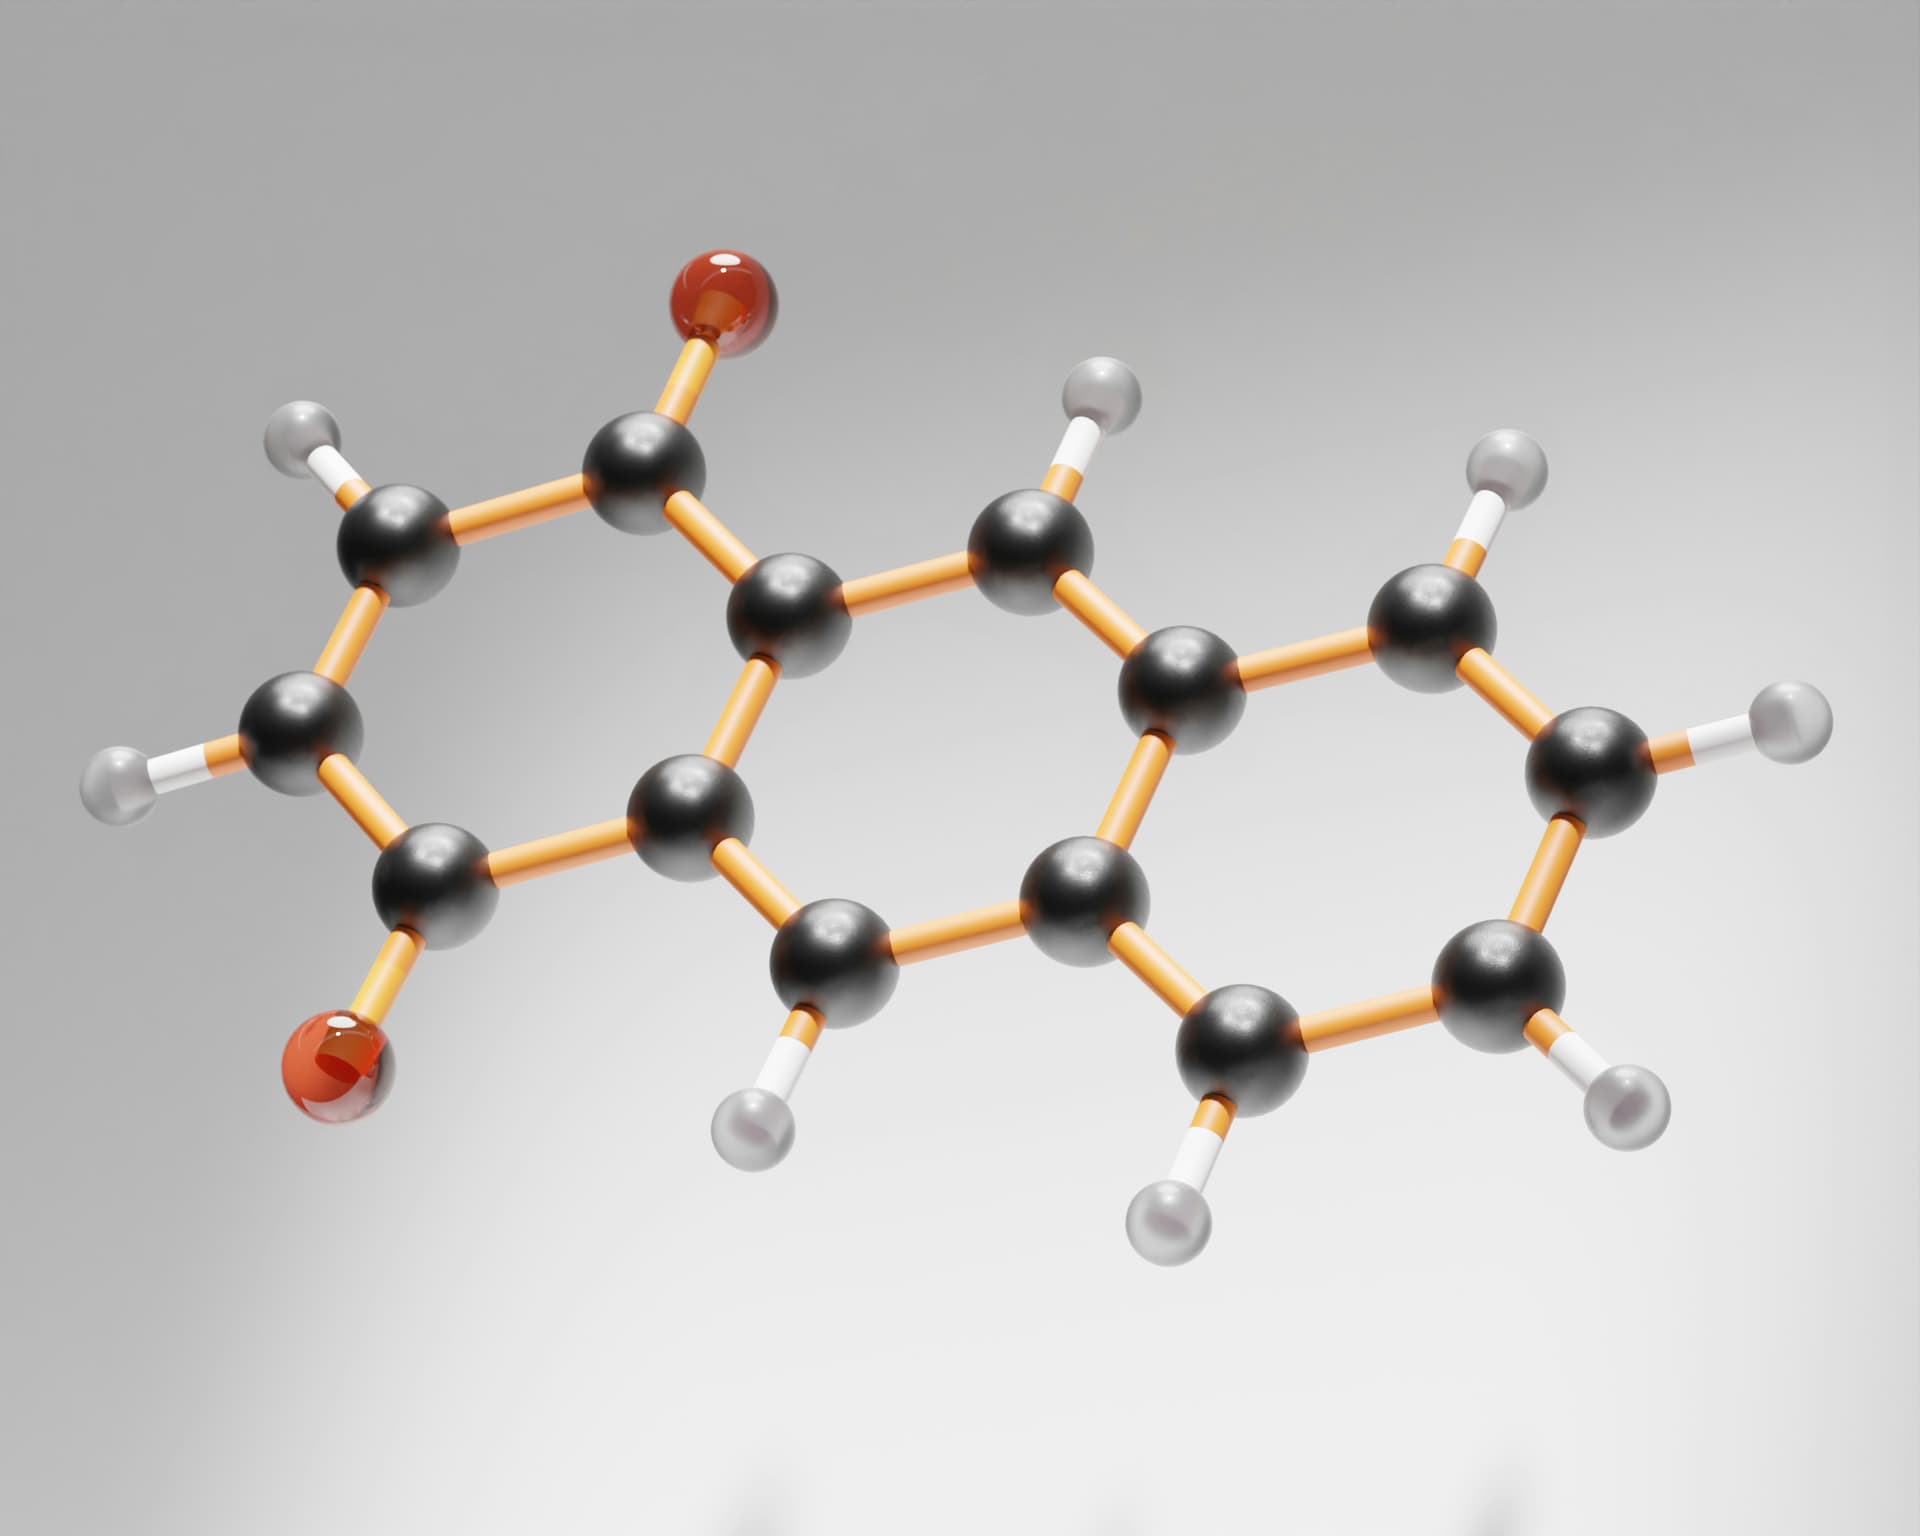
Liquid Ammonia CAS: 166412-78-8
The IEA's 2027 Surplus Forecast
The IEA projects a potential 8 million barrels/day oil supply surplus in 2027 under a scenario where:
Key assumptions include:
Full Hormuz shipping normalization
Increased non-OPEC production
Continued capacity additions
Moderate global demand growth
Market implication:
A surplus of this scale would place downward pressure on energy prices globally.
For ammonia producers, lower energy prices generally mean lower production costs.
Why This Matters for Nitrogen Fertilizers
Ammonia is the starting point for nearly every nitrogen fertilizer.
Downstream products include:
Urea
Urea (Granular) - Egypt CAS: 57-13-6
UAN solutions
Ammonium nitrate
Ammonium sulfate
Ammonium Sulphate - China CAS: 7783-20-2
When ammonia production costs fall:
Fertilizer manufacturing becomes cheaper
Producer margins improve
Fertilizer prices typically decline over time
The transmission is not immediate, but it is powerful.
The Contrast With 2026 Conditions
The fertilizer market in 2026 has been shaped by:
Major disruptions:
Hormuz shipping uncertainty
Regional production outages
Export interruptions
Elevated energy costs
These factors pushed nitrogen fertilizer prices significantly above historical averages.
Result:
Many buyers have been purchasing fertilizers at prices well above pre-crisis norms.
Tampa Benchmark: A Key Market Indicator
One of the most widely watched ammonia benchmarks is the Tampa contract price.
Pre-crisis benchmark:
Approximately $487/MT
This level is important because it reflects a market operating under relatively normal supply conditions.
Why buyers watch Tampa:
Global reference pricing mechanism
Indicator of producer sentiment
Benchmark for fertilizer cost calculations
If prices gradually move back toward historical Tampa levels, fertilizer producers would experience meaningful cost relief.
Path Toward Normalization
A return to pre-crisis pricing depends on several factors.
Positive drivers:
1. Energy market surplus
Lower oil and gas prices reduce production costs.
2. Hormuz normalization
Improved logistics reduce freight premiums and supply risk.
3. Production recovery
Middle Eastern capacity gradually returns to export markets.
4. Inventory rebuilding
Markets become less vulnerable to short-term disruptions.
What Could Delay Price Declines?
Despite the bullish cost outlook, several risks remain.
Potential obstacles:
Geopolitical instability
Any renewed disruption in energy-producing regions could reverse trends.
Natural gas market volatility
Gas prices do not always move perfectly with oil.
Strong agricultural demand
Growing fertilizer consumption can offset supply improvements.
Production discipline
Producers may manage output to support pricing.
Procurement Decision: Buy Now or Wait?
This is the central question facing ammonia importers.
Argument for Forward Contracting
Benefits:
Lock in current prices
Protect against renewed volatility
Ensure supply availability
Suitable for:
Risk-averse buyers
Fertilizer blenders with fixed commitments
Import-dependent markets
Argument for Waiting
Benefits:
Potential access to lower prices later
Capture benefits of energy market normalization
Improve procurement economics
Risks:
Unexpected supply disruptions
Seasonal demand spikes
Freight market volatility
Impact on Fertilizer Blenders
Fertilizer blenders stand to benefit significantly if ammonia costs decline.
Potential advantages:
Improved production margins
Lower raw material costs
Greater pricing flexibility
Stronger competitiveness in export markets
For many blenders, ammonia remains the single most important cost variable.
Market Outlook
The ammonia market is transitioning from a crisis-driven pricing environment toward a potentially lower-cost future. The IEA's forecast of an 8 million barrel/day oil surplus in 2027 provides a strong long-term signal that energy-linked ammonia production costs may ease significantly over the next 12–18 months.
However, markets rarely move in a straight line. Short-term supply disruptions, geopolitical developments, and seasonal fertilizer demand can still create volatility before the benefits of lower energy costs fully emerge.
For procurement teams, the challenge is balancing today's improved pricing opportunities against the possibility of even lower ammonia costs in 2027.
Key Takeaways
Ammonia production is highly dependent on natural gas and energy costs.
The IEA forecasts an 8 million barrel/day oil surplus in 2027.
Lower energy prices would reduce global ammonia production costs.
Ammonia is the primary feedstock for most nitrogen fertilizers.
Tampa ammonia settlements near $487/MT represent a key normalization benchmark.
Energy market easing could gradually lower urea and ammonia prices from 2026 highs.
Geopolitical and natural gas market risks remain important.
Importers must decide between forward contracting now or waiting for potential further declines.
Fertilizer blenders would benefit substantially from lower ammonia feedstock costs.